Weekly Real Estate News

Summary
Uplist Arcasa integration moves a zero-down FHA financing estimate into the property-shopping experience, but estimates are not approvals and zero down does not mean zero cost.
Homebuyers using Uplist’s property-payment tools can now see a zero-down FHA financing scenario alongside standard mortgage options before submitting personal information or undergoing a credit pull.
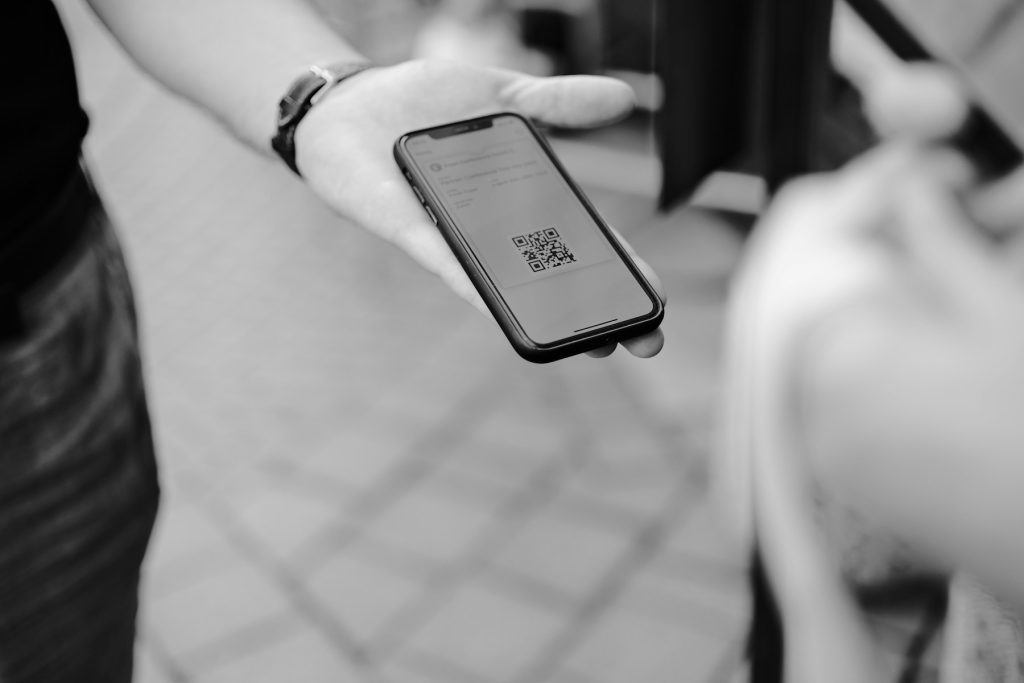
Uplist has integrated financing estimates from Arcasa into the QR codes and personalized shopping links it provides to mortgage loan officers, the companies announced Thursday.
The Arcasa structure combines down-payment assistance with solar financing inside an FHA loan. Uplist displays the estimated assistance, solar financing, monthly payment and estimated utility savings alongside conventional financing scenarios.
The companies say the integration is available through participating loan officers in 46 states. It is not currently available in Alaska, Hawaii, New York or West Virginia.
The financing scenario appears before an application
Uplist’s product is designed to put estimated mortgage payments directly into the home-shopping process. A buyer can scan a QR code on a listing flyer or open a personalized property link supplied by a loan officer.
The platform then uses Arcasa’s estimate engine to calculate the down-payment-assistance and solar components. Buyers can compare the resulting scenario without creating an account, providing a Social Security number or triggering a credit inquiry, according to the companies.
If a buyer wants to proceed, Uplist connects the shopper with the loan officer.
Zero down does not mean zero cost
The “zero-down” description refers to the buyer’s down-payment requirement under the program structure. It should not be interpreted to mean a home purchase carries no closing costs, financing costs, FHA mortgage insurance or other obligations.
Arcasa says its down-payment assistance has no income limit or first-time-buyer requirement, does not carry a separate monthly payment and does not increase the mortgage rate. Those are program claims from Arcasa and borrowers would still need to satisfy applicable FHA, lender and program requirements.
The solar component also makes this different from a generic down-payment-assistance product. Buyers and loan officers need to understand the economics and obligations of both the mortgage and solar financing rather than evaluating only the cash needed at closing.
Mortgage shopping is moving closer to the listing
The partnership reflects a broader shift in mortgage technology: financing information is increasingly appearing while consumers are browsing properties rather than after they formally contact a lender.
That can give buyers a faster view of possible monthly costs, but estimates are not loan approvals. Property taxes, insurance, mortgage insurance, borrower qualifications, interest rates and program eligibility can materially change the final payment.
For lenders, the strategic attraction is straightforward. Showing financing options at the property level gives a loan officer a chance to become part of the shopping process earlier—before the buyer has selected a home and potentially before another lender has entered the transaction.