Weekly Real Estate News
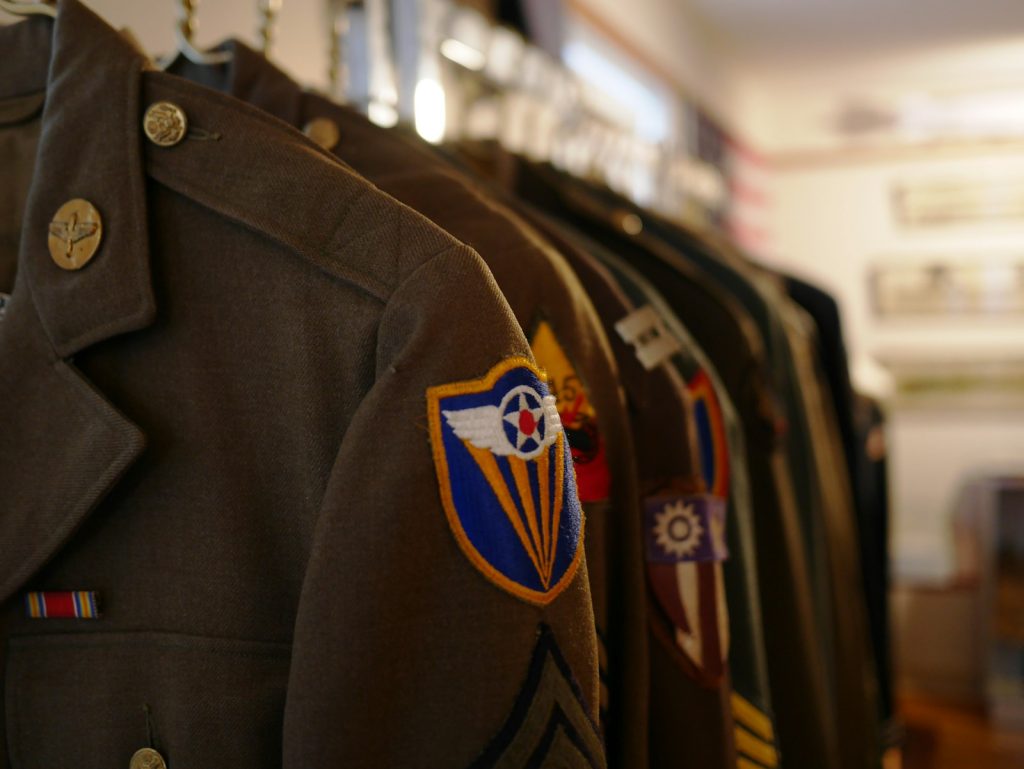
Simple Content Summary: Veterans United’s November 11 analysis estimates about 83,100 potential additional VA loans, worth $41 billion, across U.S. metropolitan markets. The estimate is a modeled opportunity based on veteran populations and VA loan use, not verified applications or guaranteed originations.
Veterans United Home Loans estimates that U.S. mortgage lenders could be missing approximately $41 billion in potential VA loan volume, an indication that the program’s growing market share may still conceal significant geographic gaps.
The lender released its analysis November 11, estimating about 83,100 additional purchase and refinance loans in metropolitan markets where VA mortgage usage was below a national benchmark relative to projected veteran populations. The company placed its comparable 2024 estimate at $37.9 billion.
A modeled opportunity, not a count of waiting borrowers
The distinction between potential and demand is essential. Veterans United’s VA Loan Opportunity Index compares each metropolitan area’s projected veteran population share with its VA loan utilization rate, then estimates a shortfall against a national benchmark. It does not establish that 83,100 qualified borrowers applied for mortgages, were denied, or would necessarily choose VA financing.



Veterans United is a major VA mortgage lender with a commercial interest in greater program use. Its findings can inform outreach and market research, but should be interpreted alongside the company’s assumptions and the underlying study methodology.
Where the gaps appear largest
New York led the lender’s metro estimates with 3,597 potential additional VA loans, followed by Philadelphia at 2,678, Chicago at 2,410, Los Angeles at 2,305 and Boston at 2,186. Detroit followed with 2,150. Denver’s metropolitan area ranked 12th with an estimated 1,472 loans.
The analysis reported that VA loans accounted for 10.04% of the U.S. mortgage market in 2025, compared with 9.80% in 2024 and 8.32% in 2023, based on Home Mortgage Disclosure Act data. Refinancing accounted for most of the recent increase. VA’s share of purchase originations rose from 8.88% in 2024 to 9.22% in 2025.
Implications for lenders and real estate agents
For originators, the estimates suggest markets where borrower education and VA-specific expertise may warrant investment. But a population-based gap is not the same as an actionable sales pipeline. Eligibility, income, credit, local prices, borrower preferences and actual loan demand still determine whether an individual transaction can close.
The findings also underscore a broader affordability issue: eligible veterans may benefit from VA loans’ potential zero-down-payment feature, but they remain subject to qualification requirements and monthly housing costs. More program awareness alone cannot eliminate local inventory shortages or affordability pressures.