Weekly Real Estate News
Summary
NAHB November 13 analysis, reiterated November 16, reports October 2026 new residential construction input prices 10.4% above October 2025 and 0.3% above September. Goods rose 9.8% annually; services 11.3%. Energy input costs declined monthly but remained 64.8% higher year over year, while building materials excluding energy rose 5.8% annually. Input-cost index, not a new-home sales-price measure. Distinct from WRE September permit story.
The cost of constructing new homes remained substantially higher in October even as monthly energy prices eased, leaving builders with a difficult combination of elevated input costs and pressure to keep new homes affordable.
The National Association of Home Builders’ November 13 analysis of the October Producer Price Index, highlighted again by NAHB on November 16, shows the price index for goods and services used in new residential construction increased 0.3% from September and 10.4% from October 2025. Those are input-price indexes, not a measure of what an individual builder paid or the final sales price of a new house.
Energy is distorting the headline
The goods index was unchanged month over month but stood 9.8% above its level a year earlier. Energy input prices fell 3.3% in October, yet remained 64.8% higher than a year earlier. Diesel fuel declined 4.6% from September but was 115.2% above October 2025. That contrast helps explain why a relatively calm monthly index can coexist with severe year-over-year cost pressure.






Excluding energy, the residential building-materials index increased 0.5% during October and 5.8% over the year. Particleboard and fiberboard rose 5.4% in the month and 13.9% over the year. Softwood veneer and plywood climbed 3.6% in October and 24.5% from a year earlier. These categories matter to framing, sheathing, cabinetry and other construction decisions, although their contribution to any particular project depends on design and purchasing contracts.
Services add another layer
Service inputs for residential construction increased 0.7% month over month and 11.3% year over year. Within that group, trade services rose 13.2% from a year earlier, transportation and warehousing services 24.6%, and other services 3.0%. Builders negotiating subcontracting and logistics arrangements may therefore encounter cost pressure beyond the lumberyard.
The numbers should not be interpreted as a prediction that new-home prices will rise by 10.4%. Builders can absorb costs in margins, adjust specifications, change incentives or renegotiate procurement, while local land costs, labor availability and demand determine how much pricing power they have. Producer price indexes describe broad categories of inputs rather than the cost structure of a specific house.
What the data mean for housing supply
The timing is important. WRE News reported separately that single-family permits declined 3.0% in the first nine months of 2026, while multifamily permits rose 4.1%. Permits measure planned construction activity, not completed homes. Together, the two reports suggest a market in which new supply faces both weaker single-family permitting and persistent input-cost inflation; they do not prove that costs caused the permitting decline.
For lenders and buyers, the distinction between construction inflation and home-price inflation is especially important. Costlier inputs can complicate project feasibility, but whether a builder can pass them through depends on mortgage rates, competing resale inventory and household purchasing power. The next monthly PPI release will help show whether October’s easing in energy prices translates into a more durable moderation in overall building costs.
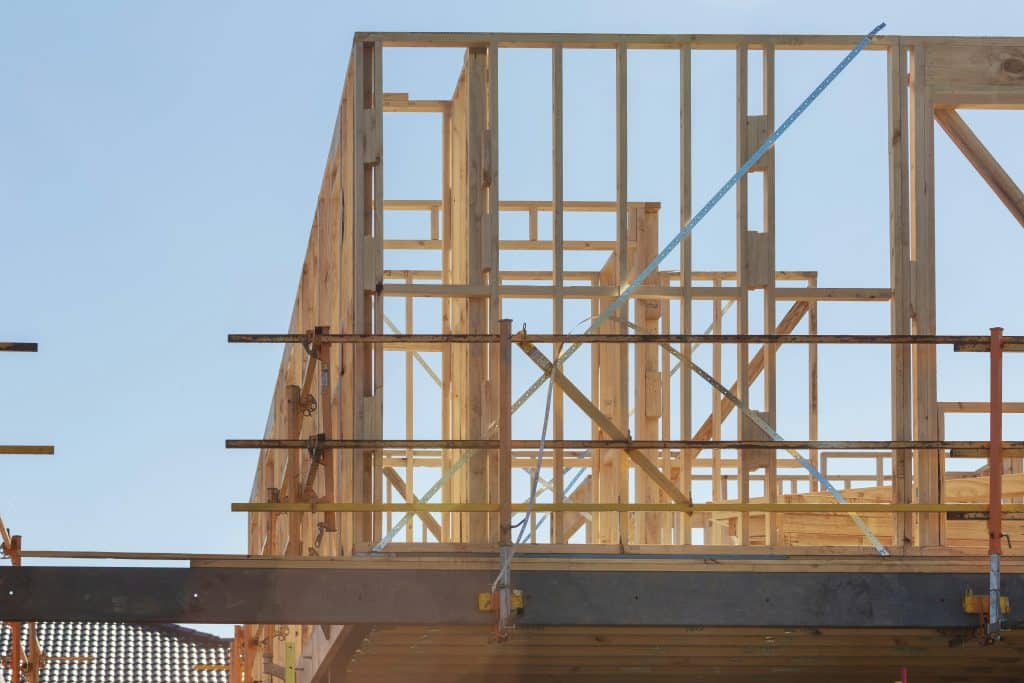
Sources: NAHB Eye on Housing, November 13, 2026, analysis of the Bureau of Labor Statistics October Producer Price Index; NAHB November 16 summary. Featured illustration: Troy Mortier / Unsplash.