

Summary
The Federal Reserve raised the federal funds target range by 25 basis points to 3.75%-4.00% on Sept. 16, its first rate increase since 2023. Updated projections show most FOMC participants expect additional tightening this year, adding pressure to a housing market already confronting mortgage rates near 7%.
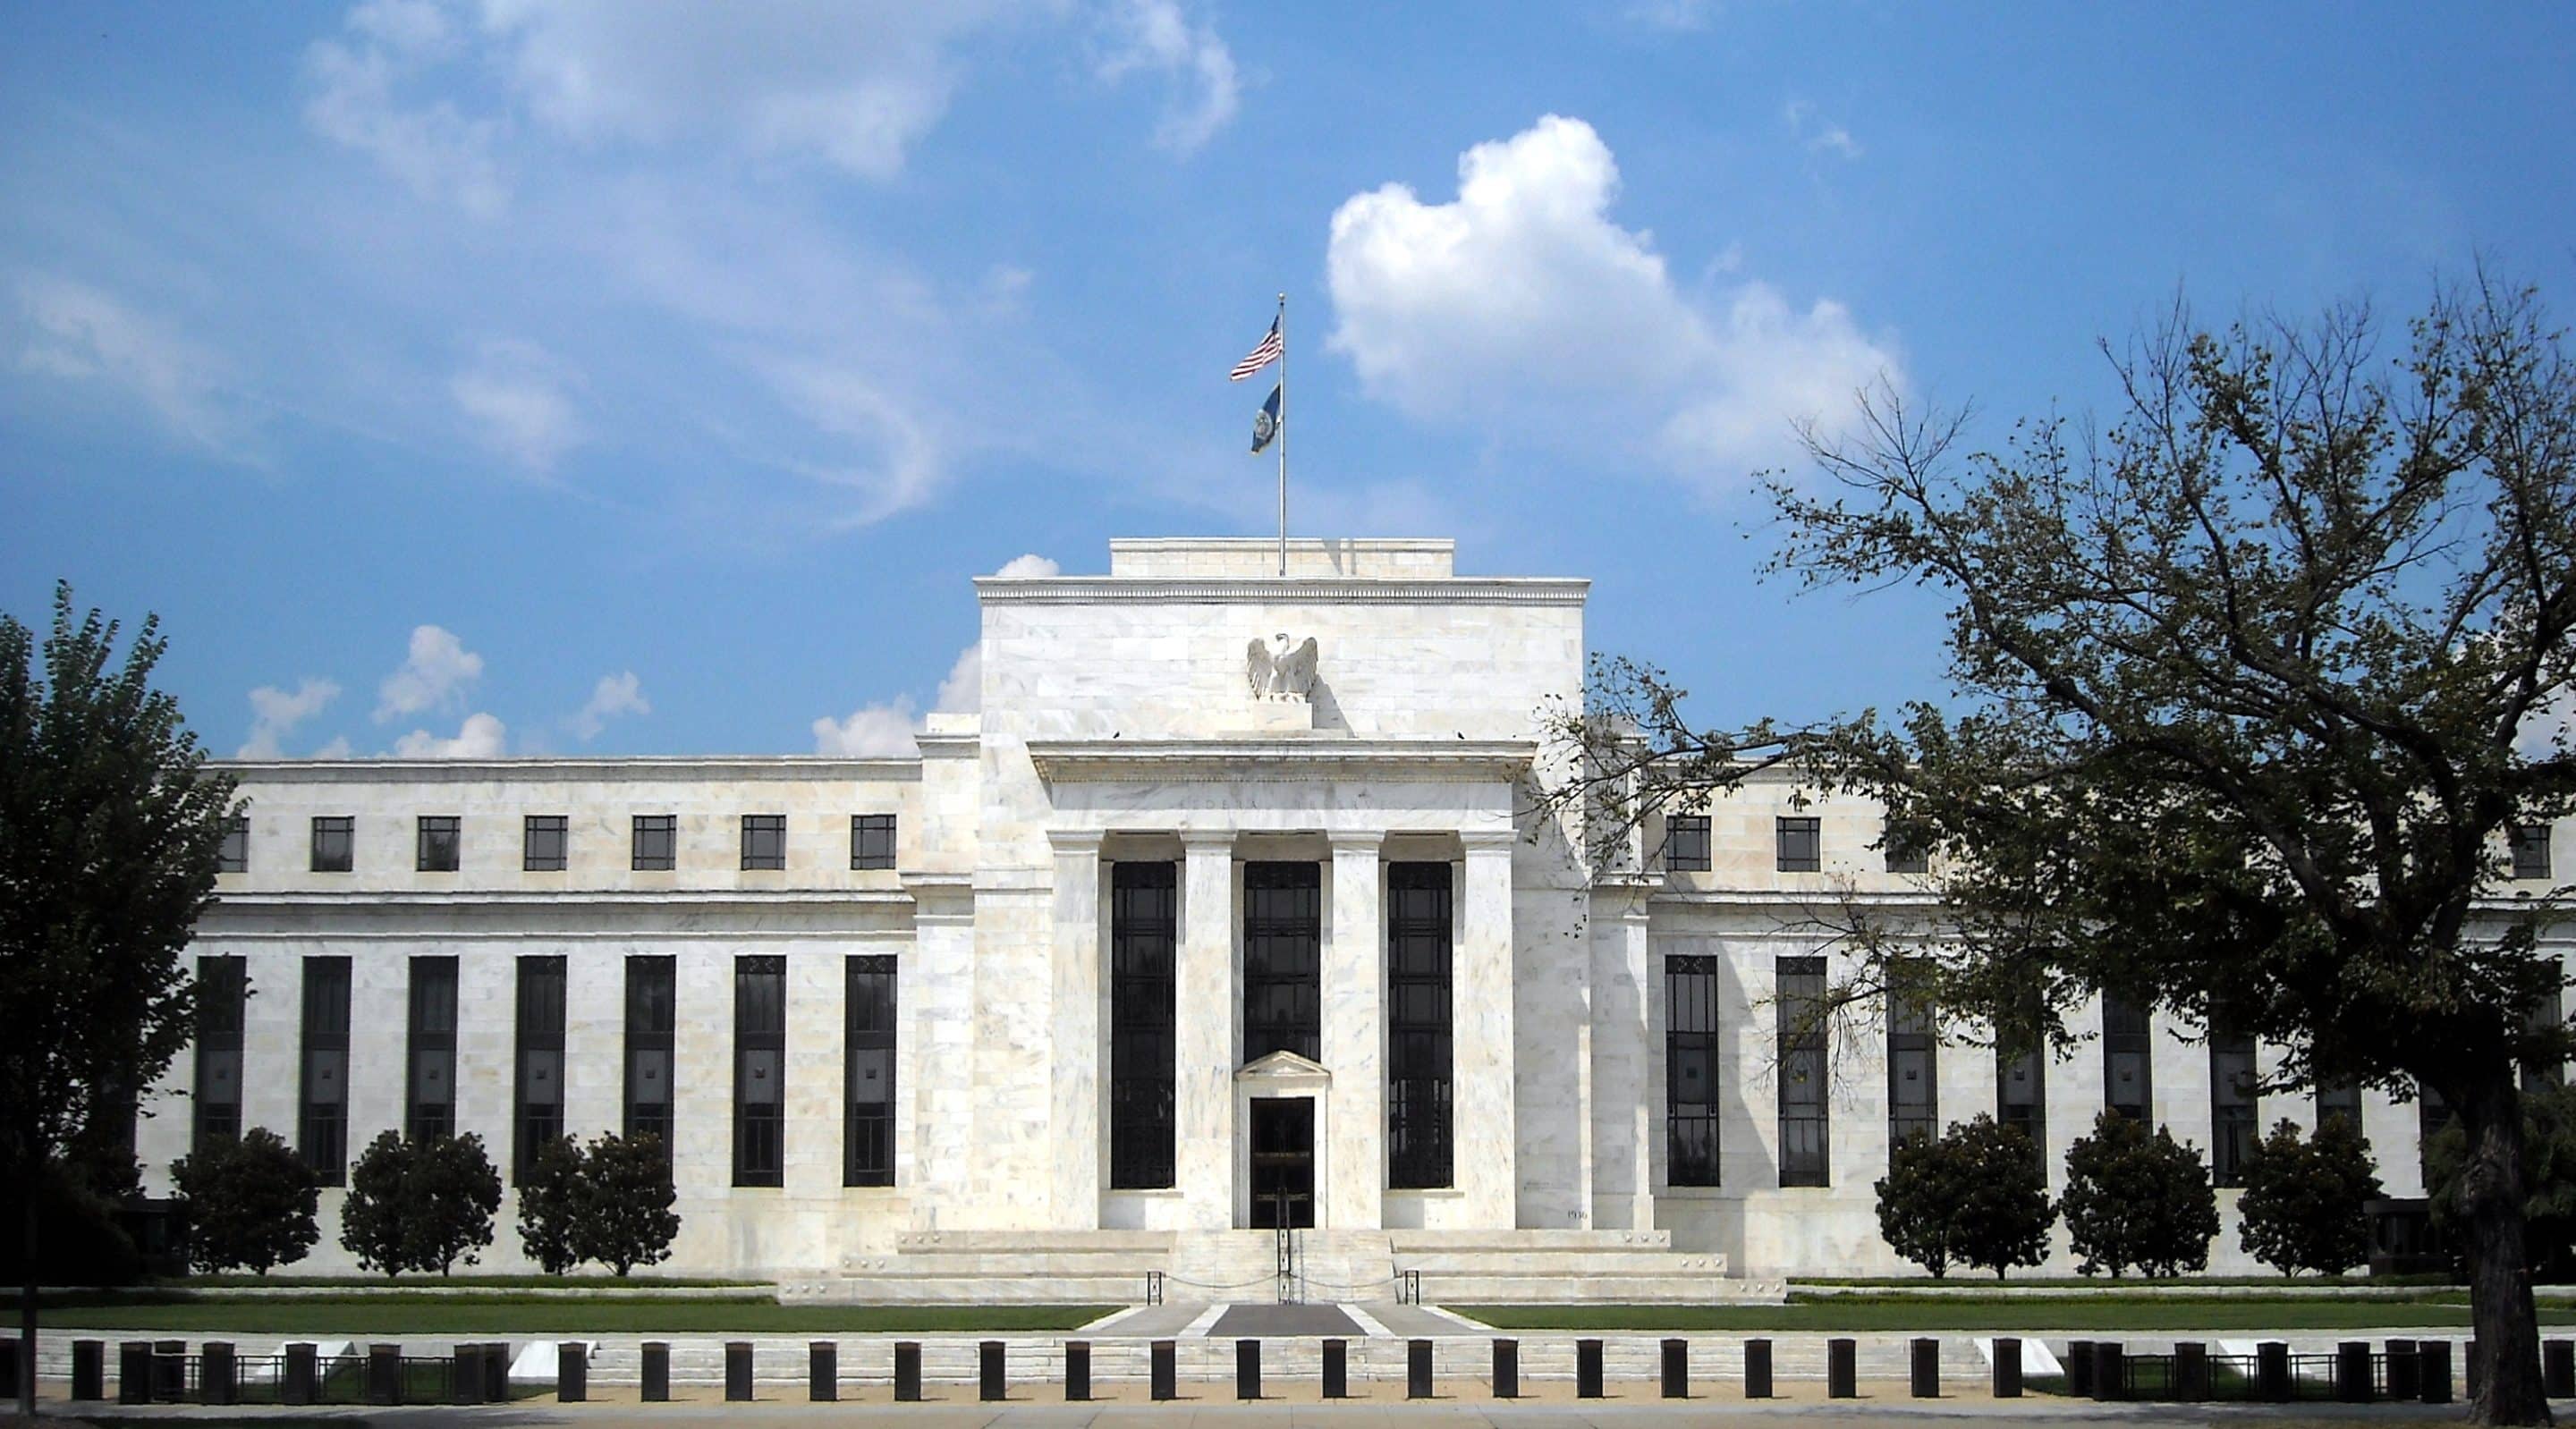
The Federal Reserve raised interest rates Wednesday for the first time since 2023, tightening monetary policy at a moment when mortgage rates are already back near 7% and the housing market is struggling with another affordability setback.
The Federal Open Market Committee voted unanimously to increase the federal funds target range by a quarter percentage point to 3.75% to 4.00%, according to the Fed’s Sept. 16 policy statement. The move ends a long stretch without an increase and reverses direction after the central bank cut rates three times late last year.
For housing, the rate increase itself is only part of the story. Mortgage rates do not move directly with the federal funds rate; they are influenced much more heavily by longer-term Treasury yields and mortgage-backed securities. Those markets had already tightened sharply ahead of Wednesday’s decision. WRE News reported Monday that the 10-year Treasury yield crossed 5%, putting fresh pressure on mortgage pricing before the Fed meeting even began.
The Fed is not signaling a quick retreat
The new rate projections are likely to matter as much as Wednesday’s quarter-point move.
In the Fed’s updated Summary of Economic Projections, the median policymaker estimate for the federal funds rate at the end of 2026 rose to 4.1%, up from 3.8% in June. Twelve of 18 participants placed their year-end estimate at a midpoint of 4.125%, while four projected 4.375%. Only two projected 3.875%, the midpoint of the new target range.
That distribution points to a committee that, as of this meeting, largely expects additional tightening rather than Wednesday’s increase being a one-and-done move. The projections are not a promise and individual policymakers can change their views as inflation, employment and financial conditions change.
The Fed also nudged its inflation outlook higher. Policymakers now project headline PCE inflation at 3.7% for 2026, compared with 3.6% in June, and core PCE inflation at 3.4%, up from 3.3%. At the same time, the median unemployment-rate projection fell to 4.1% from 4.3%, while projected real GDP growth increased to 2.3% from 2.2%.
That combination helps explain the decision. The Fed sees inflation remaining well above its 2% target without the kind of labor-market deterioration that would normally argue for easier policy.
A unanimous vote after months of disagreement
Wednesday’s increase was approved 12-0. The unanimity is notable after policymakers had shown visible disagreement earlier in the year over whether rates should move higher, lower or remain unchanged.
The FOMC said economic activity continues to expand at a solid pace, domestic spending has remained resilient and job gains have kept pace with growth in the workforce. Inflation, however, remains elevated. The committee said the increase would support a more timely return to its 2% inflation goal.
Chairman Kevin Warsh had already made clear that housing weakness would not by itself dictate Fed policy. In August, WRE News reported that Warsh acknowledged strain in housing but said inflation remained the central bank’s predominant concern.
Wednesday’s vote puts that position into policy.
Mortgage rates had already moved before the Fed
The immediate mistake for borrowers and housing professionals would be to assume a 25-basis-point Fed increase automatically means a 25-basis-point increase in mortgage rates.
Bond markets had spent days pricing in the possibility of tighter policy. The 10-year Treasury yield reached levels around 5% ahead of the meeting, and daily mortgage-rate trackers moved above 7% even while Freddie Mac’s lagged weekly survey remained below that threshold.
That distinction now becomes more important. If investors believe the Fed is finally getting ahead of inflation, longer-term yields could stabilize or retreat even with a higher overnight policy rate. If markets instead conclude that inflation will require several more increases, Treasury and mortgage rates could remain elevated or move higher.
The Fed’s projections give the housing industry little reason to count on a rapid policy reversal. WRE News reported Tuesday that a Reuters survey of housing analysts had already pushed expected mortgage-rate relief further out, with forecasters raising their outlook for borrowing costs over the coming quarters.
Housing now has to absorb another tightening cycle
The timing is difficult for a market that has yet to recover normal transaction volume from the last rate shock.
Home prices remain high relative to incomes, many existing owners still carry mortgages far below current market rates, and builders have leaned heavily on incentives and rate buydowns to keep buyers moving. Higher long-term borrowing costs also reach beyond the standard 30-year mortgage, affecting construction finance, warehouse lines, home-equity borrowing, multifamily debt and commercial real estate.
Wednesday’s decision does not settle where mortgage rates go next. The bond market will continue to react to inflation, employment, energy prices, federal borrowing and the Fed’s own guidance. But the policy direction has changed: after nearly three years without an increase, the Federal Reserve is raising rates again, and most policymakers currently expect the new 3.75%-4.00% range will not be the peak for 2026.




0 Comments