Weekly Real Estate News

Summary
Warburg Pincus reaffirmed its nonbinding A$5.25 per security Ingenia proposal, added distribution protection of up to A$0.05, and demanded board confirmation and exclusive due diligence by October 19. Ingenia has made no recommendation and continues to evaluate its Peet acquisition.
Warburg Pincus has given Australian residential property operator Ingenia Communities until Monday to open exclusive due diligence and declare its A$5.25-a-security takeover proposal preferable to Ingenia’s planned acquisition of Peet Limited, sharpening a contest over the company’s future without yet putting a binding buyout on the table.
In an Australian Securities Exchange announcement dated October 15, Ingenia said the private equity firm had reaffirmed its cash proposal after reviewing initial due diligence materials. Warburg Pincus now calls the price its “best and final” offer unless a superior proposal emerges. It has also changed the treatment of a prospective distribution: securityholders could retain up to A$0.05 per security for the half-year ending December 31 without reducing the A$5.25 price.
The deadline is unusually consequential because Warburg Pincus is asking for more than permission to examine financial records. Before exclusive diligence begins, Ingenia’s board must confirm that the proposed takeover, if completed on its terms, would be more favorable to investors than the Peet acquisition. That assessment would remain conditional on satisfactory further diligence, mutually agreed definitive documents and the absence of a superior proposal.






Ingenia has not given that confirmation. The board said it is reviewing the amended approach with financial and legal advisers, has not formed a view on its merits or conditions and makes no recommendation to investors. The company emphasized that there is no certainty of a binding offer or completed transaction.
Two different paths for Ingenia
The proposed takeover would put Ingenia under private ownership through a scheme of arrangement. The alternative is Ingenia’s own proposed acquisition of Peet, an Australian residential land developer, intended to expand its development pipeline and establish a larger housing platform. The choices involve different risks: a cash exit at a stated price on one side, and a strategic expansion requiring integration and execution on the other.
Ingenia announced its proposed Peet acquisition on August 26. Its October 7 investor presentation and transaction update described Peet’s development portfolio and possible land-lease conversion opportunities. The transaction remains subject to conditions, including establishment of a Flagstone joint venture, and the company’s timetable then contemplated completion in December.
Warburg Pincus has already made several approaches. Ingenia’s October 7 presentation identifies an initial A$4.75-a-security proposal received August 30 and a revised A$5.05 proposal received September 14, both rejected as materially undervaluing the company. A further A$5.25 proposal followed in late September. On October 5, Ingenia agreed to give Warburg Pincus initial, nonexclusive due diligence access without endorsing the takeover.
The October 15 changes do not increase that A$5.25 headline cash price. They clarify that investors may keep a limited upcoming distribution and press Ingenia to commit to a more exclusive process. The revised distribution treatment could improve the effective amount received by an eligible securityholder if the transaction proceeds and the distribution is paid, but neither the distribution nor the acquisition is guaranteed.
Why the land-lease business matters
Ingenia owns, operates and develops accommodation focused heavily on Australia’s older residents, alongside rental villages and holiday parks. In Thursday’s announcement it said it had 96 communities and development sites across its Ingenia Lifestyle, Ingenia Gardens, Ingenia Holidays and Ingenia Rental businesses. Its business combines recurring site-rental income with development and tourism exposure.
For a buyer such as Warburg Pincus, land-lease communities offer a different revenue profile from conventional homebuilding. Residents generally own or occupy homes while paying recurring fees for the underlying site and associated services. Development of additional sites can expand that income base, though construction costs, occupancy, consumer demand and regulation remain material variables.
The proposed Peet combination would expand Ingenia’s development exposure. Ingenia’s October presentation argues that Peet’s land inventory could support future communities and broader capital partnerships. Those benefits are the company’s strategic expectations, not realized synergies, and shareholders must weigh them against the certainty—or lack of it—of Warburg Pincus’s preliminary cash proposal.
The price comparison alone cannot settle the question. A$5.25 is a proposed consideration per stapled security, not an accepted purchase price. A takeover under a scheme of arrangement would still require binding documentation, applicable approvals and other customary steps. The issuer has not announced an agreed scheme with Warburg Pincus.
Monday’s deadline is the immediate test
Warburg Pincus wants Ingenia to deliver the board confirmation and grant exclusive access to outstanding due diligence materials, subject to a mutually acceptable process deed, by October 19. A confirmation would not itself mean shareholders had approved a takeover or that Peet had been abandoned. It would signal that the board was prepared to prioritize an exclusive examination of the private-equity alternative under the specified conditions.
Ingenia could instead decline those conditions, seek different terms or continue pursuing the Peet transaction. The announcement gives no basis to predict which course the directors will take. Investors have been told they need not act at this stage.
For the wider real estate industry, the contest is a significant test of how private capital values an established land-lease housing operator against the longer-term prospects of a large residential development pipeline. The immediate facts are narrower: Warburg Pincus has not raised its stated cash price, Ingenia has not recommended the proposal, and Monday is the next disclosed deadline.
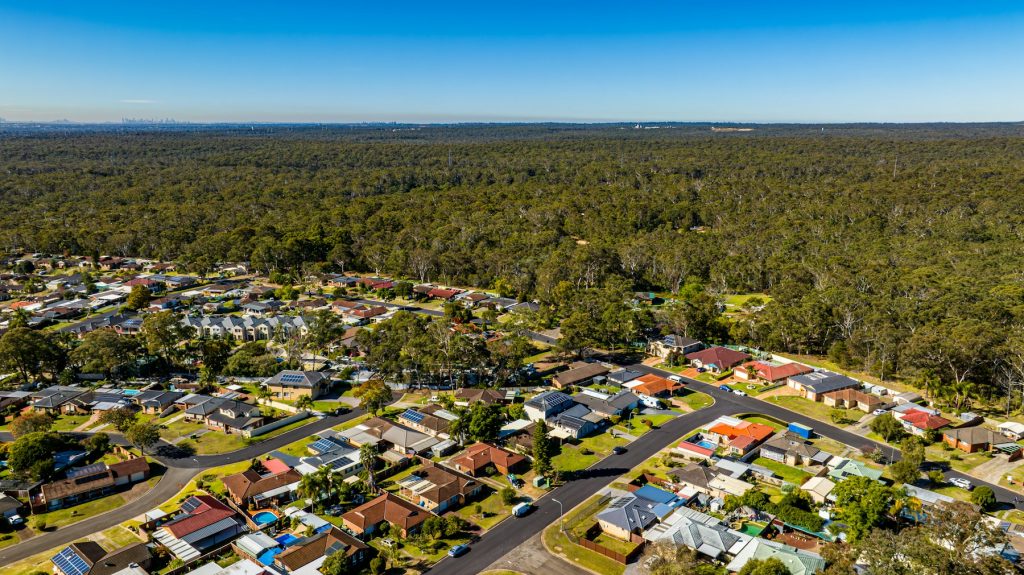
Featured image: Australian residential housing bordering bushland. Shanjir H/Unsplash; illustrative, not an Ingenia or Peet property.