Weekly Real Estate News
In brief: The benchmark 10-year U.S. Treasury yield finished Friday at 5.00% on the Treasury Department’s daily par-yield series, up from 4.96% Thursday, while Brent crude settled at $116.72 a barrel. For mortgage lenders and homebuyers, the combination keeps inflation and funding costs in focus even after this week’s modest relief in quoted mortgage rates.
The Treasury Department’s October 23 yield-curve table lists 5.00% for the 10-year note, compared with 4.96% October 22 and 5.13% October 21. These are end-of-day par-yield observations, not mortgage rate quotes. Intraday trading sources may report a slightly different figure; Reuters put the 10-year yield at about 4.99% late Friday.
Although the yield rebounded four basis points Friday, it was still below Monday’s 5.15% Treasury reading. That matters because a one-day increase should not be mistaken for a weeklong surge. Investors have been balancing inflation concerns against demand for safer government bonds as global markets fluctuate.
Oil prices complicate the outlook
Brent crude settled at $116.72 a barrel Friday, according to Reuters’ October 23 market report. Oil’s increase reflected renewed worries about disruptions to Middle East energy supplies. Higher energy prices can raise transportation, manufacturing and construction costs and may reinforce inflation expectations, though their effect on Treasury yields depends on the broader economic outlook.






The direct connection to mortgages is not one-for-one. Mortgage-backed securities trade at yields that incorporate prepayment and credit-related risks as well as investor demand, so the spread between a 30-year mortgage rate and the 10-year Treasury can widen or narrow. Lenders also price loans based on pipeline hedging, borrower characteristics and loan terms.
Weekly mortgage survey had shown a decline
Freddie Mac’s October 22 survey put the average 30-year fixed mortgage rate at 7.32%, down from 7.40% the previous week. WRE News reported that release Thursday. The survey reflects lender quotations collected before Friday’s market close; it is not an immediate readout of the latest Treasury move.
For prospective buyers, the practical effect is continued uncertainty around affordability. A rate near 7.3% keeps principal-and-interest payments elevated relative to the sub-6% borrowing environment briefly seen earlier in the year. Whether Friday’s bond-market move changes consumer mortgage pricing will depend on subsequent market sessions and lender rate sheets.
What commercial real estate investors are watching
Longer-term Treasury yields also influence the cost of financing office, multifamily, industrial and other property assets. A higher risk-free benchmark can put pressure on property valuations if rents and operating income do not rise enough to offset financing costs. The effect varies considerably by lease structure, leverage, loan maturity and the investor’s cost of capital.
For lenders, the more important question is whether yields stabilize after the recent volatility. A four-basis-point daily change alone is not evidence of a new financing crisis, and the October 23 data do not establish that mortgage rates have reversed their weekly decline.
The Federal Reserve’s next policy decision and subsequent inflation readings will provide further context. Until then, Friday’s close is a reminder that a small improvement in weekly mortgage surveys can coexist with stubbornly high long-term borrowing costs and volatile energy prices.
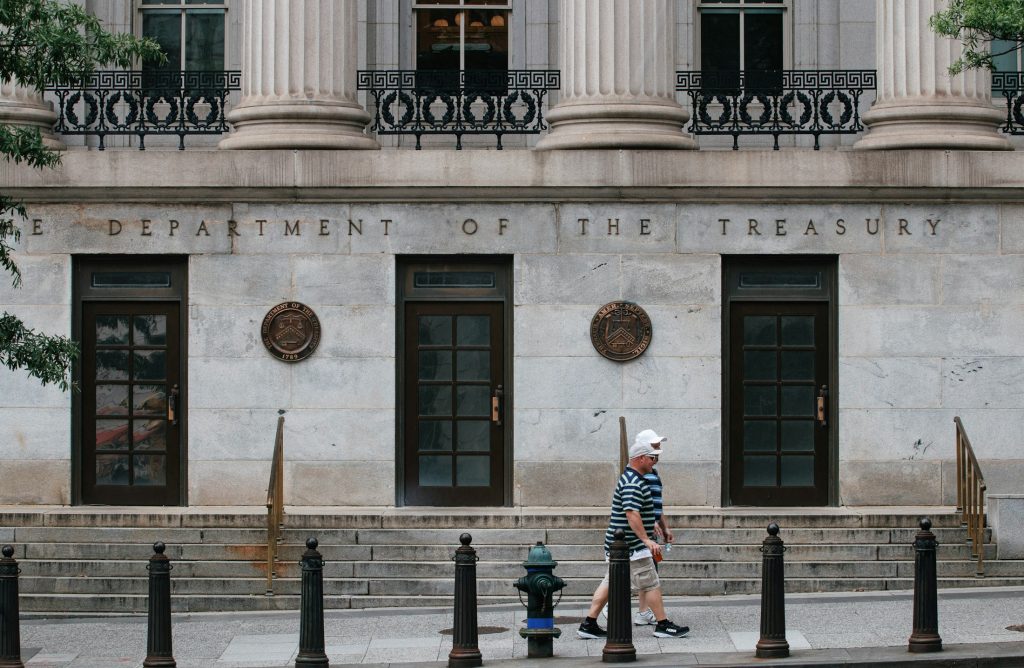
Image: U.S. Treasury Department building, illustrative. Photo: Connor Gan / Unsplash.