Weekly Real Estate News
Summary
Allied Properties REIT's board cut the monthly distribution 90% to C$0.006 per unit starting in November 2026, aiming to retain about C$126 million annually for debt reduction. Office occupancy was 84.9%, while net debt reached 12.5 times annualized adjusted EBITDA. Additional property sales are pending regulatory approval and closing.
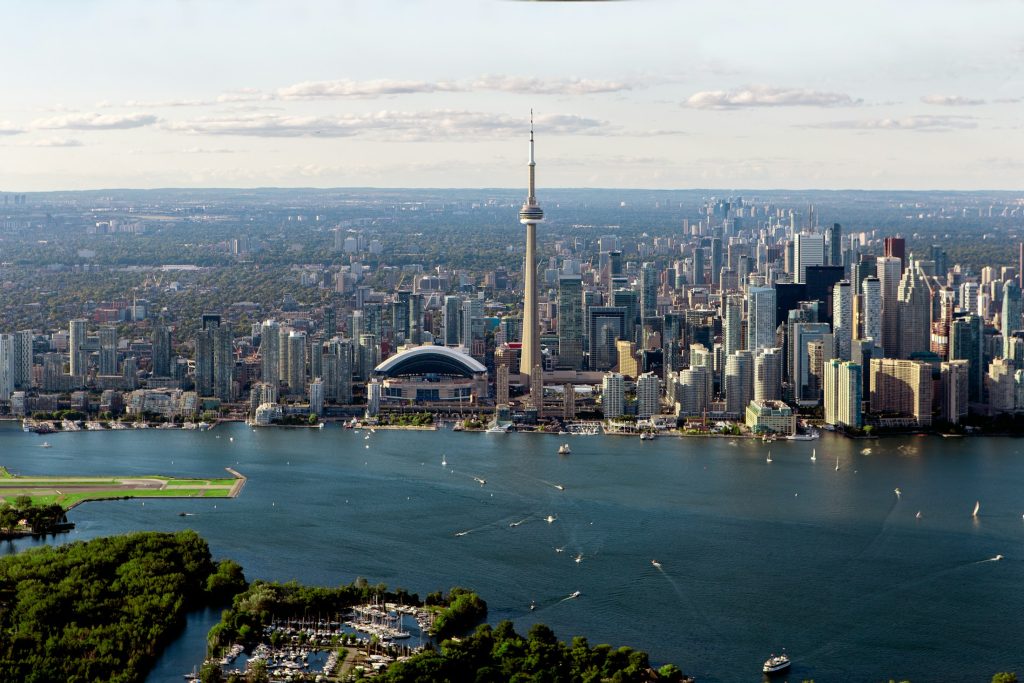
Allied Properties Real Estate Investment Trust is cutting its monthly distribution by 90%, an unusually steep reduction that makes the Toronto office landlord’s balance-sheet repair the immediate priority even as leasing conditions improve.
The trust’s board reduced the monthly payment to C$0.006 per unit beginning in November, or C$0.072 on an annualized basis. Allied estimates the change will retain about C$126 million a year for debt reduction, according to its October 28 third-quarter announcement. The distribution cut is a board decision, while the projected cash retention depends on future conditions.
Allied’s occupancy and leasing figures offer a more complicated picture than the distribution decision alone suggests. At September 30, 84.9% of its space was occupied and 86.8% leased, both above the company’s expectations. Signed leases can precede actual occupancy and rent commencement, so the two percentages describe different stages of demand.






Debt remains the harder problem. Allied reported net debt of 12.5 times annualized adjusted EBITDA for the nine months ended September, up from 12.0 times in the second quarter. It attributed part of the change to ceasing recognition of interest income on loans related to Westbank. The company expects property-sale proceeds to bring that leverage measure down to the mid-11-times range by year-end. That target is management’s forecast, contingent on transactions closing.
Allied completed C$321 million of dispositions by the announcement date and had about C$15 million more under firm agreement, bringing secured gross proceeds to roughly C$336 million. After quarter-end, sales involving Toronto House and 19 Duncan became firm, subject to Competition Act approval. If those deals close as anticipated in the fourth quarter, total secured gross disposition proceeds would approach C$660 million. The company did not describe the pending sales as completed.
It is also expanding its multiyear disposition program by another C$750 million to C$1.5 billion. Such a program can reduce debt, but property sales also remove rental income from the portfolio. Investors will be watching whether the improvement in leverage outpaces the earnings lost through asset disposals.
Funds from operations, excluding specified adjustments, were C$0.194 per unit in the third quarter. Allied said the figure reflected lower interest income. FFO is a widely used non-GAAP real estate measure; it is not the same as net income or cash available for distributions.
Chief Executive Cecilia Williams said stronger leasing had allowed Allied to raise its year-end occupancy outlook, but reducing leverage remained the top priority. The scale of the distribution cut shows management is willing to make a significant near-term concession to unit holders to preserve cash.
The report comes as commercial property owners across North America face different outcomes depending on asset quality and debt maturities. WRE News recently reported on Brandywine Realty Trust’s property sales and debt reduction in the U.S. office market. Allied operates in Canada, with its own financing structure and portfolio, so the two results should not be treated as directly comparable.
Two dates now matter: the November distribution change and the expected fourth-quarter completion of pending property sales. The latter remains subject to regulatory approval and closing conditions, and a failure or delay would complicate Allied’s year-end debt target.