Weekly Real Estate News
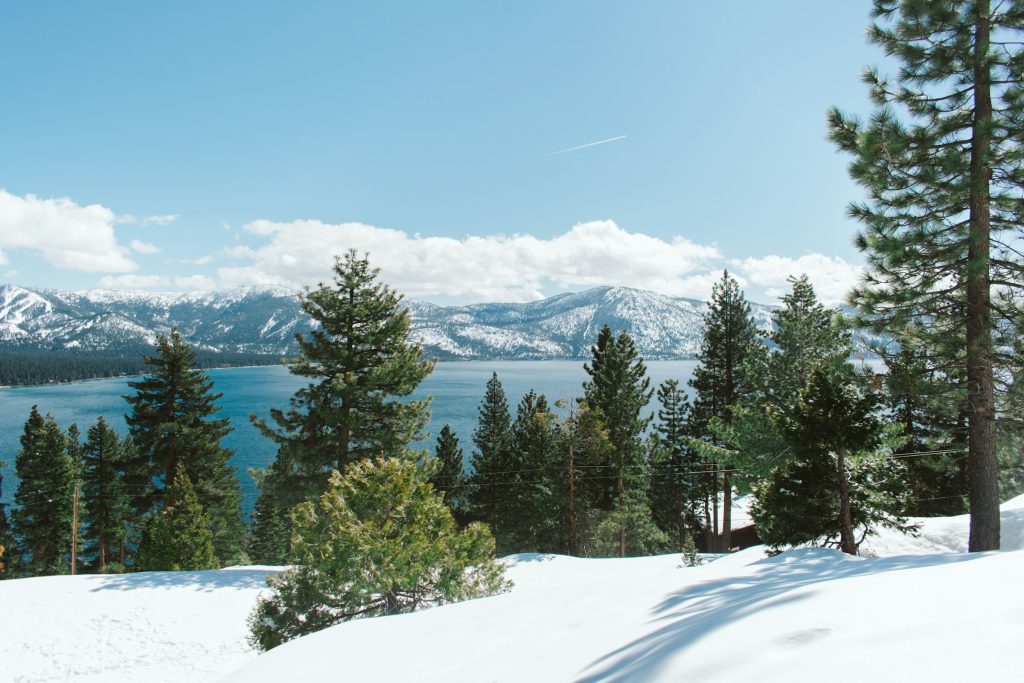
Braemar Hotels & Resorts has refinanced the mortgage on its 170-room Ritz-Carlton Lake Tahoe property in Truckee, California, replacing a loan due in early 2027 with a larger facility and a lower interest-rate spread.
The company announced the completed refinancing November 3 at 8 a.m. Eastern. The previous loan carried an outstanding balance of $43.4 million, bore interest at the secured overnight financing rate, or SOFR, plus 3.25 percentage points, and was scheduled to mature in January 2027.
New loan provides additional capital and time
The replacement mortgage totals $60 million, with an additional $15 million potentially available for future draws if specified conditions are met. That means the committed initial amount is $60 million; the extra $15 million should not be counted as money already borrowed.
The new facility carries a floating rate of SOFR plus 2.65 percentage points, a 60-basis-point reduction in the spread compared with the old mortgage. Because both loans float with SOFR, the spread reduction does not by itself establish the total change in the property’s borrowing cost over time.



Braemar said the new loan has an initial three-year term and two options to extend it by one year each. Extension rights can depend on conditions and fees, which the company’s short announcement did not detail. It also did not name the lender or disclose transaction expenses.
According to management, the transaction pushes Braemar’s next hard debt maturity to December 2028. That statement reflects the company’s current debt schedule and does not mean it has no other financial obligations before then.
Why the refinancing matters
A refinancing can do several things for a hotel owner: replace an approaching maturity, change interest-rate exposure and release or add capital. Here, the transaction addresses all three to varying degrees. It removes the immediate January 2027 mortgage deadline, increases the stated loan principal and reduces the floating-rate margin.
The difference between the $60 million new facility and the $43.4 million old balance is $16.6 million before fees, reserves and other uses. The announcement does not specify how much net cash Braemar retains after closing costs or any property-level requirements, so that difference should not be characterized as unrestricted cash proceeds.
The property is a luxury mountain resort, a segment where revenue can vary with travel demand, seasonality and capital expenditure needs. Hotel values and loan terms also depend on the property’s operating results and lender underwriting, neither of which was provided in the refinancing announcement.
Debt-market signal, not a universal benchmark
The 60-basis-point spread reduction suggests Braemar obtained more favorable pricing on this particular asset. It is not evidence that every hotel borrower can refinance at the same spread or that broader commercial mortgage rates have fallen by an equivalent amount.
Investors will be watching how the new debt affects interest expense, whether the optional draws are used and how the resort performs through its next operating seasons. The immediate, verified development is a completed mortgage refinancing that lengthens the repayment runway for a named property.