Weekly Real Estate News
Summary
Realtor.com's November 17, 2026 third-quarter New-Construction Insights report found new-home buyers had average starting mortgage rates of 5.01%, versus 6.15% for existing-home buyers, partly reflecting temporary builder buydowns. Permanent 30-year fixed rates averaged 6.19% and 6.68%, respectively. Median new-home listing prices were $451,071, nearly unchanged from a year earlier, while new-home inventory grew 0.1%. The article distinguishes temporary and permanent rate relief, explains geographic mix and compares listing rather than transaction prices.
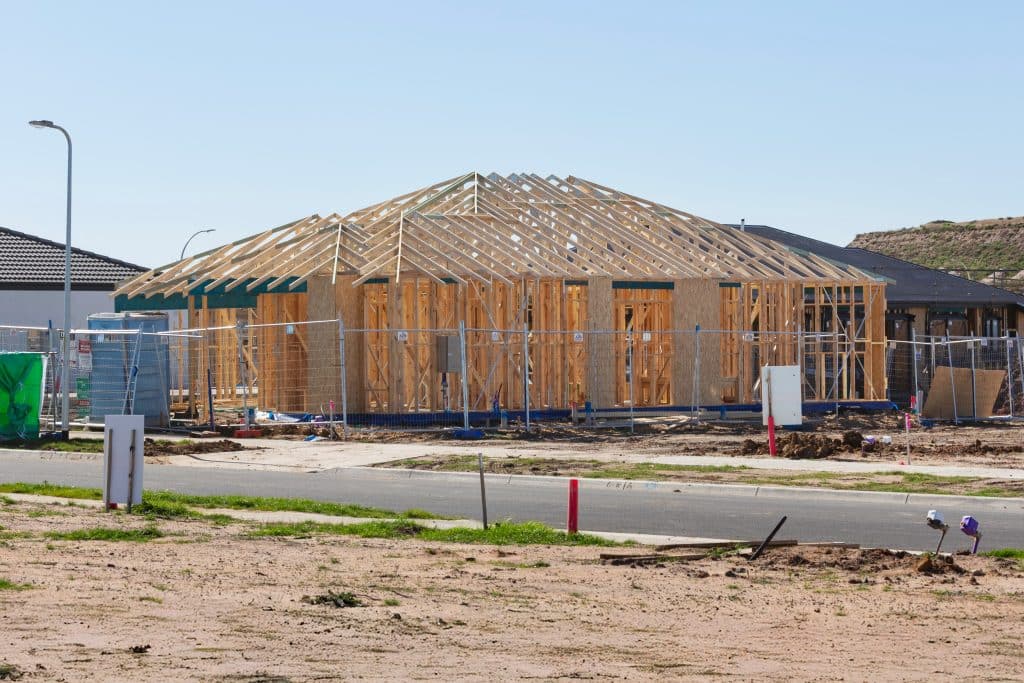
Homebuilders are using mortgage-rate discounts to compete for buyers while keeping advertised home prices largely unchanged, according to new third-quarter research from Realtor.com. The gap between financing costs on new and existing homes is now substantial enough to change the monthly cost of ownership even when the asking prices are similar.
The November 17 New-Construction Insights report found that buyers of newly built homes started mortgages at an average 5.01% rate in the third quarter, compared with 6.15% for buyers of existing homes. That 1.14-percentage-point difference includes temporary rate reductions, so it should not be mistaken for a permanent discount available to every new-home purchaser.
Rate incentives change the comparison
Realtor.com estimates that the rate difference translates to approximately $258 less in first-year monthly interest on a $400,000 home purchase with 10% down. The analysis also isolated mortgages carrying a fixed rate for the full 30-year term: new-home buyers averaged 6.19%, against 6.68% for resale buyers. That smaller, lasting difference was worth an estimated $117 per month in interest under the same purchase assumptions.






The distinction matters for borrowers. A temporary buydown may reduce the initial payment for one, two or three years before the contractual rate applies. A permanent rate reduction lowers the rate over the entire term. Buyers comparing builder financing packages with resale properties need to examine the note rate, buydown schedule, closing costs, lender conditions and the payment after any temporary subsidy expires.
Builders can arrange concessions through affiliated or preferred lenders or fund them directly. Those incentives can help sell inventory without resetting the publicly advertised price of an entire development. For the buyer, however, a lower initial payment is only one part of the transaction’s economics; the purchase price, loan balance, taxes and insurance still determine the longer-term obligation.
Prices remain steady as supply growth stalls
The median listing price of a newly built home reached $451,071 in the third quarter, close to its level in the same quarters of 2024 and 2025. The median existing-home listing price was $402,883, down 1.5% from a year earlier. Those national medians reflect different mixes of homes and locations and cannot establish the premium for comparable properties in a single neighborhood.
New-home inventory increased just 0.1% from a year earlier, while existing-home inventory rose 3.1%. Newly built homes accounted for 16.7% of listings, down from 17.2% a year before. Price reductions appeared on 20.9% of new-home listings and 21.6% of existing-home listings. Both figures point to sellers adjusting to slower demand, although they do not measure the size of individual discounts.
The report also shows why a national price comparison can mislead. New homes were larger at the median—2,056 square feet against 1,790 for resale homes—but their median asking price per square foot was $218, slightly below the $219 figure for existing homes. New construction is concentrated more heavily in the South and in suburban markets, where land and housing costs differ from those in older, expensive metropolitan neighborhoods.
Realtor.com’s figures are based on its listing inventory through September and mortgage-rate information drawn from public records. The financing comparison is observational; it does not show that every builder will offer a given rate or that borrowers with different credit profiles will qualify on identical terms.
For lenders and agents, the findings underscore the need to compare total financing terms rather than advertised rates alone. For builders, the growing use of rate incentives presents a trade-off: preserve headline prices while absorbing part of buyers’ borrowing costs. Whether that strategy can continue will depend on financing costs, margins and the pace at which unsold homes move.
Related WRE coverage: single-family permitting trends and construction input-cost pressures.