Weekly Real Estate News
Summary
NAHB November 17 2026 analysis of Census 2025 Survey of Construction: custom homes were 19.6% of single-family starts, up from 17.5% in 2024. Custom starts reached 182869. New England 47.0% versus West South Central 12.7%.
Custom homes accounted for a larger share of U.S. single-family construction in 2025, even as the industry continued to wrestle with high financing costs and uneven demand across regions.
An analysis released November 17 by the National Association of Home Builders, using the Census Bureau’s Survey of Construction, found that custom homes represented 19.6% of all single-family starts in 2025, up from 17.5% in 2024. The share increased alongside the number of custom homes started, which rose to 182,869 from 176,932.
What counts as a custom home
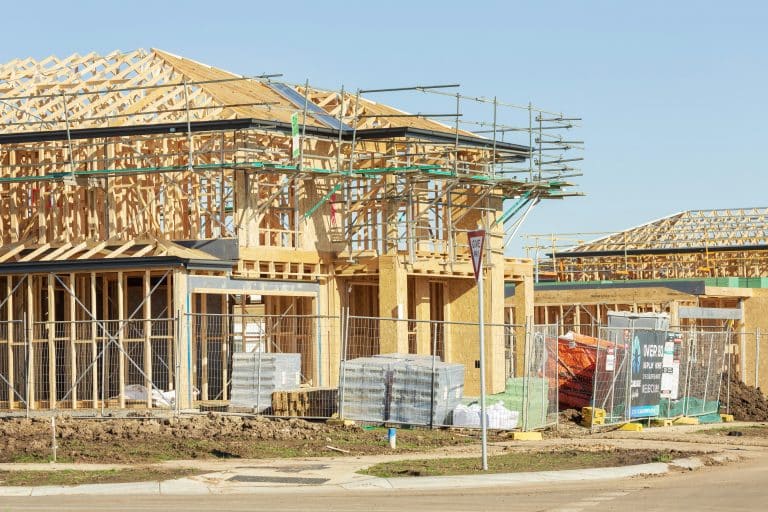
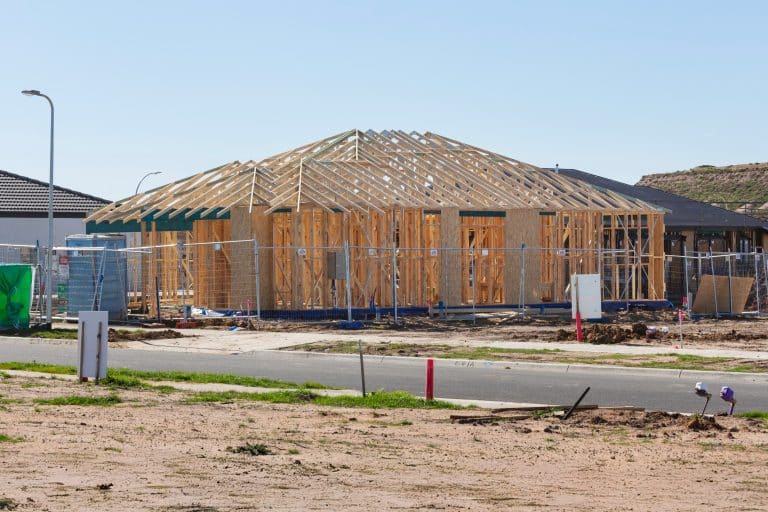
The survey’s custom category includes contractor-built and owner-built homes constructed individually for occupancy by their owners on land the owners hold. It is not a catchall term for an expensive or highly customized house offered for sale in a subdivision. That distinction matters when comparing this segment with speculative building and homes built for rent.






According to the same annual data, 71.8% of single-family starts in 2025 were homes built for sale, while 8.6% were built for rent. Those categories and custom construction together account for the survey’s single-family starts.
New England’s share stands apart
The geographic breakdown shows how different the market structure can be from one region to another. In New England, custom homes made up 47.0% of single-family starts in 2025. At the other end of the spectrum, the West South Central division recorded a 12.7% share, the Mountain division 13.7%, and the South Atlantic division 15.7%.
These are shares of each region’s construction activity, not shares of the national custom-home total. A high percentage does not necessarily mean a region builds more custom homes in absolute numbers than a larger or faster-growing region with a lower percentage.
Why the distinction matters for builders and lenders
Building on an owner’s land changes the financing and sales process. A custom-home project may involve a construction loan, a construction-to-permanent loan, a different appraisal process and closer coordination among the borrower, builder and lender than a completed speculative home purchase. The survey does not establish that custom projects are uniformly less sensitive to interest rates or that their owners are all cash buyers.
Custom-building activity also differs from the inventory of finished homes offered for sale. A custom start generally reflects an owner commissioning construction, while a speculative start can add a home to a builder’s for-sale inventory. That distinction can affect how economists interpret shifts in construction activity and the availability of homes to buyers.
Annual data versus the latest quarterly figures
NAHB said the custom-home share remained broadly flat in quarterly 2026 statistics. Those more timely reports do not offer the same geographic detail as the annual Survey of Construction, so the regional percentages in the new analysis describe 2025 rather than current-quarter 2026 conditions.
The findings add another dimension to WRE News coverage of diverging single-family and multifamily permit trends. The permitting report addresses the volume and type of authorized projects; the custom-home analysis instead examines the purpose for which single-family homes were started.
For builders, lenders and agents, the central lesson is that a national construction number can mask very different local business models. The custom market’s share rose nationally, but its role varies widely by region, and changes in that share should not be mistaken for a uniform recovery in homebuilding.
Primary source: NAHB Economic Research, November 17, 2026, based on U.S. Census Bureau Survey of Construction data.