Weekly Real Estate News
Summary
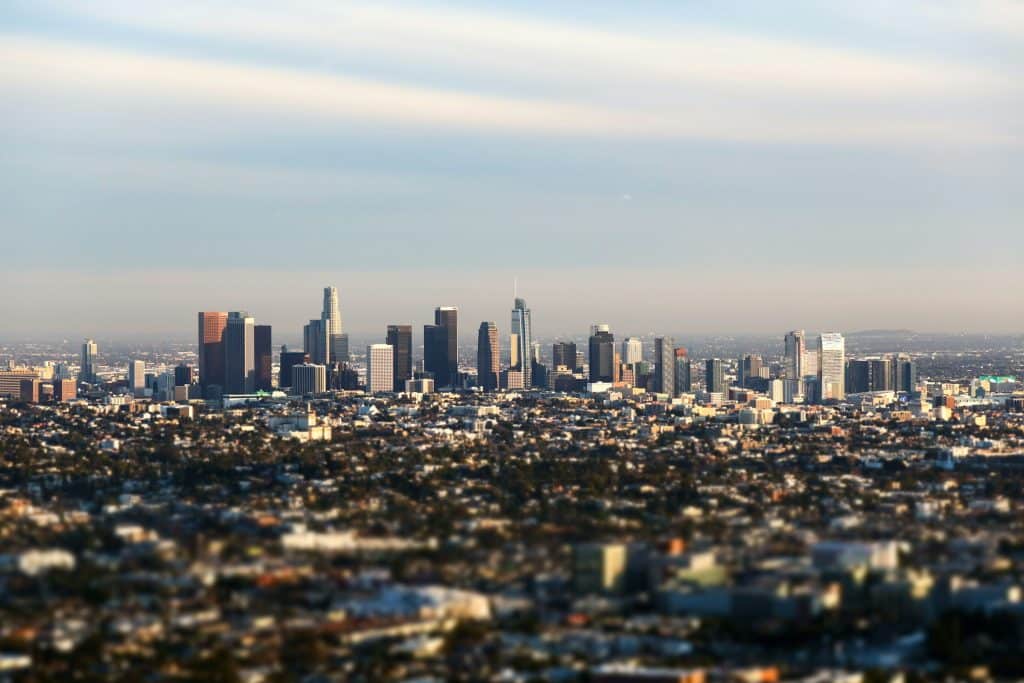
PwC and ULI's 2027 outlook ranks Dallas-Fort Worth first for a third year, based on views of nearly 1,500 participants. Financing costs, public policy, demographics, supply and submarket selection are central themes.
Dallas-Fort Worth leads the Urban Land Institute and PwC’s list of U.S. real estate markets to watch in 2027 for a third consecutive year, but the annual industry outlook carries a broader warning: investors and developers face a market in which capital is available while execution is becoming more difficult.
The organizations released their 48th annual Emerging Trends in Real Estate report on October 27, drawing on surveys and interviews with nearly 1,500 industry participants across the United States and Canada. The findings represent respondents’ outlooks, not a forecast of guaranteed investment returns.
Markets to watch
Dallas-Fort Worth takes the top spot, followed by Nashville, Miami, Raleigh-Durham and San Francisco. The report also singles out Manhattan, Phoenix, Orange County, Columbus and Seattle for closer examination. These rankings describe perceived investment and development prospects rather than current home-price appreciation or transaction volume.






The rankings illustrate a change in how investors evaluate locations. A metropolitan area’s overall population or employment growth may not be enough to justify a deal when construction costs, insurance expenses, rent restrictions, local supply and financing terms vary sharply among neighborhoods and property types.
Eight forces shaping the market
The report organizes its findings around eight themes: federal fiscal pressures and Treasury yields; investment beyond traditional property categories; the growing role of public policy in location decisions; demographic change; differences among submarkets; a potential development supply gap; artificial intelligence alongside human expertise; and large-scale district development tied to institutions and infrastructure.
One of the central conclusions is that the market is not experiencing uniform distress. Higher financing costs and looming loan maturities can create pressure on individual properties, while functioning debt markets and repricing can create opportunities for well-capitalized buyers. Those conditions do not mean every distressed asset is attractively priced or every property sector is recovering.
In housing, the report distinguishes a broad need for more homes from the narrower supply of homes that households can afford and developers can build profitably. It also points to aging households and regionally uneven migration as important demand drivers. That suggests developers must evaluate local incomes, absorption and household composition rather than relying on national shortage estimates alone.
Why lenders and developers should pay attention
For mortgage and commercial real estate lenders, the findings reinforce the importance of property-level underwriting, debt maturity schedules and realistic refinancing assumptions. Developers face the separate challenge of deciding whether projects delayed by high costs today may encounter less competing supply when they are eventually delivered.
The authors also identify growing interest in operational and infrastructure-related assets, including data centers, cold storage and senior housing. Those categories can have specialized utility, staffing and regulatory demands that differ from conventional office, retail or apartment investments.
Artificial intelligence is another theme, but the report cautions against equating adoption with proven operating gains. Data quality, governance and implementation costs remain material obstacles. Human market knowledge and relationships continue to matter when capital decisions involve complicated local conditions.
The report’s overall message is neither a blanket recovery call nor a prediction of widespread collapse. It describes a more selective investment environment in which capital availability, policy, operating performance and the quality of individual assets determine outcomes.
Sources: PwC and ULI October 27 announcement; full Emerging Trends in Real Estate 2027 report and methodology.