Weekly Real Estate News
OTTAWA, Oct. 28, 2026 — The Bank of Canada raised its benchmark interest rate by a quarter percentage point Wednesday, ending a three-year stretch without a rate increase as persistent inflation threatens to keep borrowing costs elevated for Canadian homebuyers and homeowners.
The central bank increased its target for the overnight rate from 2.25% to 2.50%, with the Bank Rate set at 2.75% and the deposit rate at 2.45%. The official policy announcement was scheduled for 9:45 a.m. Eastern, or 7:45 a.m. Mountain. It was the first increase since July 2023.
Inflation concerns outweigh weak housing activity
Policymakers cited a stronger Canadian economy and the risk that persistently high energy costs will spread into a wider range of consumer prices. Canada’s annual consumer price inflation has been around 3% since April. The bank expects inflation to reach approximately 3.5% by the end of 2026 and average 3% in 2027 before moving back toward its 2% target in the middle of 2028.
Economic growth has been stronger than the bank anticipated in July, including 3.3% annualized growth in the second quarter. Yet the central bank’s October Monetary Policy Report expects housing activity to remain relatively weak. It projects Canadian economic growth of 1% in 2026 and 2% in each of the next two years.






The bank signaled that further tightening is possible but did not commit to another increase. Its next scheduled rate decision is December 9.
What the increase means for mortgages
The immediate impact is most direct for borrowing products tied to lenders’ prime rates, including many variable-rate mortgages and home-equity lines of credit. Depending on a loan’s terms, an increase can raise monthly payments or shift a larger share of a fixed payment toward interest, slowing principal repayment.
Existing fixed-rate mortgage payments generally do not change solely because the central bank raises its overnight rate. Borrowers renewing fixed-rate mortgages, however, face prevailing market rates at renewal. Those rates are influenced substantially by government bond yields and do not necessarily move point-for-point with the policy rate.
For buyers already confronting affordability pressures, higher financing costs can reduce the mortgage amount they qualify for. The bank’s own expectation of relatively weak housing activity suggests policymakers recognize the strain on the market, even as they prioritize containing inflation.
Why the policy reversal matters
The increase marks a shift from the Bank of Canada’s extended pause at 2.25%. The last change before Wednesday had been a quarter-point cut in October 2025. A renewed tightening cycle would be especially consequential for households approaching mortgage renewals, although the timing and scale of any further increases remain uncertain.
The bank’s decision also highlights a broader tension facing housing markets: inflation may require restrictive monetary policy even when homebuying activity is subdued. It does not establish that every Canadian lender has raised mortgage rates or that home sales have already declined in response to Wednesday’s decision.
Simple Content Summary
The Bank of Canada raised its overnight interest rate to 2.50% on October 28, 2026, its first rate increase since 2023. Persistent inflation prompted the move even though the central bank expects housing activity to remain weak. Variable-rate borrowers and homeowners with home-equity lines of credit may face higher costs; fixed-rate mortgage impacts depend on loan terms and bond-market conditions.
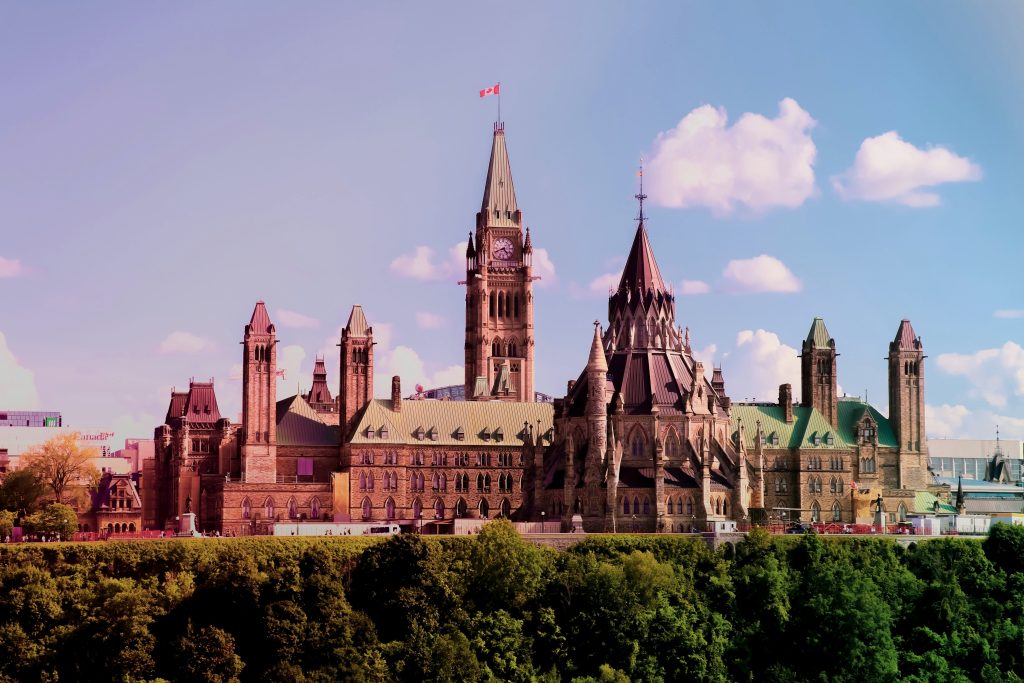
Sources: Bank of Canada policy decision, Oct. 28, 2026; Monetary Policy Report, October 2026. Featured photograph: Philip Yu / Unsplash; Parliament Hill in Ottawa, illustrative and not the Bank of Canada headquarters.