Weekly Real Estate News

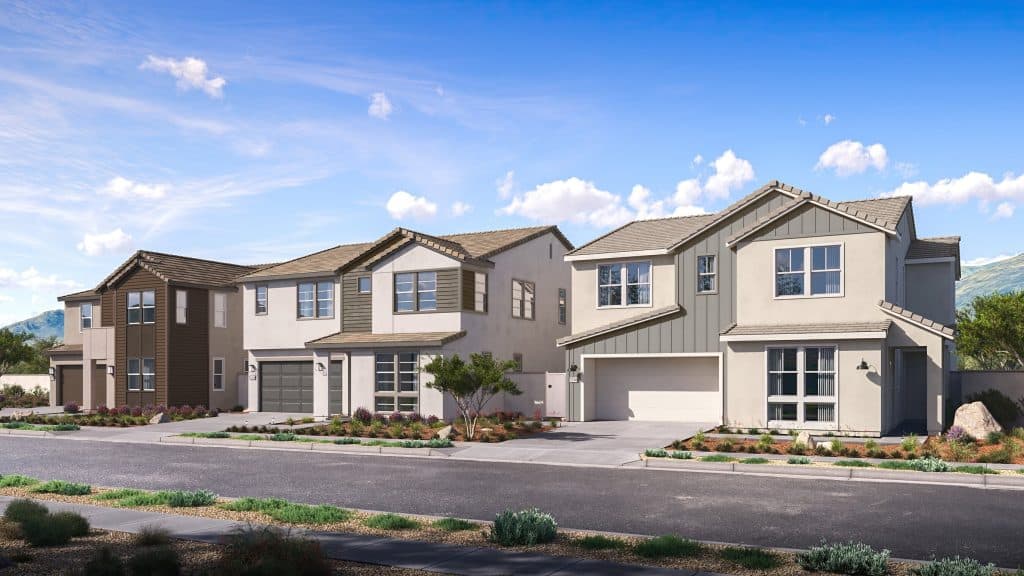
California voters will decide next month whether to authorize as much as $25 billion in revenue bonds to help middle-income buyers purchase newly built homes with second mortgages covering up to 17% of the purchase price.
Proposition 37, the California Middle-Class Homeownership and Family Home Construction Act, appears on the Nov. 3 ballot. Under the official state voter materials, the California Housing Finance Agency would be authorized—but not required—to issue up to $25 billion in revenue bonds and use the proceeds to finance fixed-rate loans for eligible buyers of qualifying newly constructed homes.
The structure is designed to attack the down-payment barrier without a general-fund appropriation. A buyer could contribute as little as 3% while the program finances as much as another 17%, potentially bringing the combined equity contribution to 20% before the buyer’s primary mortgage.
A $25 billion housing-finance experiment
The proposal is limited to newly constructed houses and condominiums that meet the program’s price requirements. The ballot language describes eligible homes as priced below roughly $1.5 million.
Borrowers would have to be California residents, occupy the property and meet income limits. Reporting on the measure indicates eligibility would extend to households earning as much as twice area median income.
The second mortgage would not be a grant. Buyers would repay it in monthly installments. The bonds would be repaid from mortgage payments rather than the state General Fund, and the official fiscal analysis says the measure would create no direct state or local government costs.
That distinction matters. Proposition 37 is not a $25 billion taxpayer-funded down-payment giveaway. It would authorize a large lending platform financed through revenue bonds, with repayment tied to the mortgages made under the program.
The measure deliberately ties buyer assistance to new supply
Unlike broad down-payment assistance that can be used on existing homes, Proposition 37 limits financing to qualifying new construction. Supporters argue that design can help buyers while also increasing demand for newly built housing, giving builders more confidence to add supply.
The approach also attempts to answer a longstanding criticism of demand-side housing subsidies: giving buyers more purchasing power in a supply-constrained market can simply bid up existing home prices. Restricting the program to new homes does not eliminate that risk, but it ties the financing mechanism to production rather than the resale market.
Supporters include real estate and labor interests. Their argument is that California’s home prices make conventional down payments unattainable for many middle-income households and that the program can widen ownership without putting repayment risk on the state treasury.
Opponents argue the state should not expand its role in mortgage lending and say the proposal does not address the underlying land, regulatory and construction costs that make California housing expensive. They also contend that helping households borrow more can increase indebtedness rather than solve affordability.
The leverage deserves scrutiny
The mechanics can be illustrated with an $800,000 home. A 3% buyer contribution would equal $24,000. A 17% second mortgage would equal $136,000, leaving a conventional first mortgage to finance the remaining 80%, before accounting for closing costs and other program terms.
That structure could reduce the cash barrier dramatically, but it does not reduce the home’s price. The buyer still carries repayment obligations associated with both mortgages. Qualification standards, interest rates, underwriting and the interaction between the first and second liens will therefore determine how much monthly-payment relief the program actually provides.
For lenders and builders, the measure could create a substantial new channel if voters approve it and CalHFA implements the full authorization. For buyers, its usefulness would vary by income, local new-home prices and the financing terms available when they purchase.
The $25 billion figure is a ceiling, not a guarantee that the full amount would be issued. The measure authorizes CalHFA to borrow up to that amount.
What happens next
California’s general election is Nov. 3. If Proposition 37 passes, implementation would move to CalHFA and the bond market, where program rules, loan pricing and issuance timing would determine how quickly financing becomes available.
The proposition deserves national attention because it combines two policy ideas that are often treated separately: homebuyer assistance and housing production. If implemented at scale, California would be testing whether a state-backed secondary financing structure can make ownership more accessible while steering demand toward new supply.