 Weekly Real Estate News
Summary
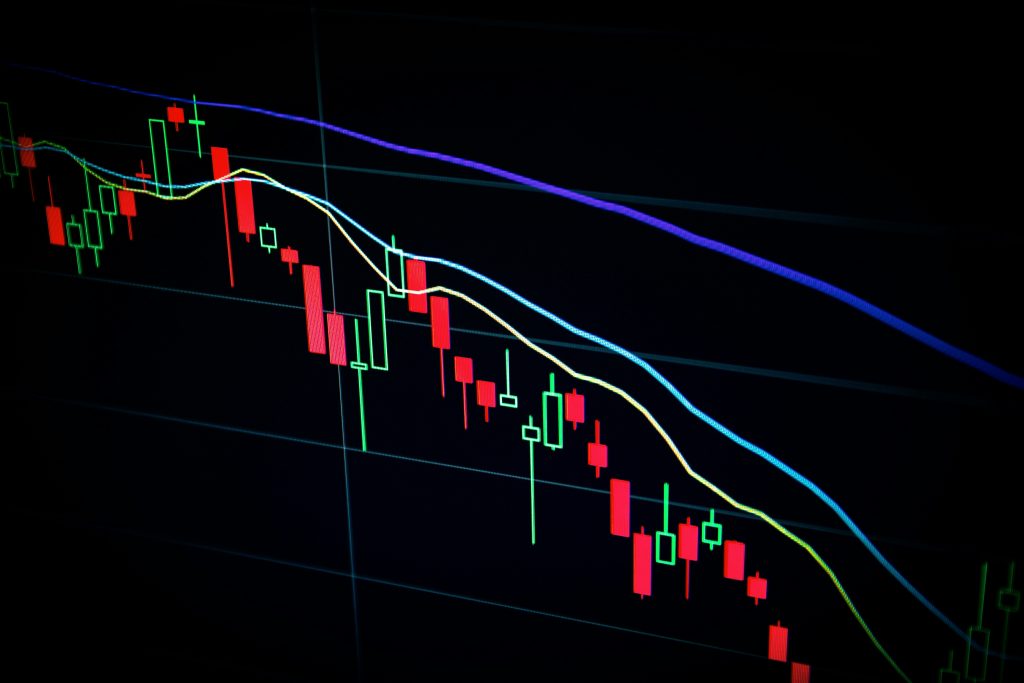
Fair Isaac shares fell roughly 27% on Sept. 29, their worst one-day decline since 1989, after FHFA moved toward a single Fannie Mae and Freddie Mac mortgage-pricing grid incorporating VantageScore alongside Classic FICO. The closing loss deepened materially from the 20%-plus intraday decline WRE News initially reported.
Fair Isaac Corp. shares collapsed roughly 27% Tuesday, their worst one-day decline since 1989, as investors confronted a sharper threat to FICO’s long-dominant position in U.S. mortgage credit scoring.
The closing selloff was substantially deeper than the 20%-plus decline seen when WRE News first reported the move Tuesday morning. Reuters put the full-session loss at 26.5%, while Barron’s reported a 27% decline and identified it as Fair Isaac’s largest one-day drop since 1989. The stock fell as much as 29% intraday.
The selloff followed Federal Housing Finance Agency Director Bill Pulte’s announcement that Fannie Mae and Freddie Mac are moving toward a single mortgage pricing grid that incorporates VantageScore alongside Classic FICO. Fair Isaac finished as the worst-performing stock in the S&P 500.






The size of the move matters to the mortgage industry because Wall Street is attaching a financial consequence to a policy transition that, until recently, was largely discussed in terms of lender choice and credit-score modernization.
WRE News reported earlier Tuesday that the enterprises are moving to one pricing grid incorporating VantageScore alongside Classic FICO. Pulte has not yet published the replacement grid or an implementation date, leaving the borrower-level pricing effects unresolved.
Mortgage scoring is a major FICO business
Fair Isaac’s own financial results show why investors are sensitive to changes in mortgage scoring.
In its fiscal third-quarter earnings report, the company said Scores revenue reached $458.9 million, up 41% from a year earlier. Business-to-business Scores revenue increased 49%, with FICO saying the gain was primarily attributable to a higher unit price for mortgage-origination scores.
Total company revenue for the quarter ended June 30 was $674.2 million, up 26% from a year earlier.
That pricing power has increasingly become part of the policy fight. Pulte has publicly criticized FICO’s pricing and has pushed Fannie Mae and Freddie Mac to expand the use of VantageScore 4.0. The enterprises have expanded VantageScore availability across their approved lender bases.
FHFA’s current credit-score policy says lenders may choose either Classic FICO or VantageScore 4.0 for eligible loans sold to the enterprises. FICO Score 10T has also been approved, but it is not currently eligible for loan delivery.
FICO, meanwhile, has defended the predictive performance of its newer 10T model and has argued that comparisons among scoring systems should focus on risk performance as well as price.
A second major FICO selloff this month
Tuesday’s decline is not the first time the credit-score transition has hit Fair Isaac’s market value.
FICO shares fell about 20% in early trading on Sept. 4 after Pulte directed Fannie Mae and Freddie Mac to approve all lenders to use VantageScore. At the time, he wrote that FICO had “enjoyed a monopoly” and said that would no longer be the case.
The latest selloff comes after a further escalation: the move from simply expanding lender access to VantageScore toward incorporating the competing score into the GSE mortgage-pricing framework.
The distinction is important. The pricing grids used by Fannie Mae and Freddie Mac help determine loan-level price adjustments on conventional mortgages. Credit score is one of the characteristics used in that pricing process, along with factors such as loan-to-value ratio.
Exactly how the new framework changes individual loan economics cannot yet be determined. FHFA has not released the unified grid or a timetable for putting it into effect.
That uncertainty makes Tuesday’s stock reaction a market judgment rather than evidence that a specific amount of FICO mortgage revenue will disappear. Lenders can still use Classic FICO under current GSE rules, and FICO 10T remains an approved model planned for future enterprise use.
The competitive pressure is also moving from policy into lender operations. Rocket Mortgage announced Monday that it will make VantageScore 4.0 its preferred scoring model for eligible loans during the fourth quarter after roughly four months of testing.
By Tuesday’s close, investors had delivered their clearest verdict yet on the financial risk to Fair Isaac: a roughly 27% one-day loss, the company’s worst since 1989.
FICO and their competitors are surveillance entities, no one voted for them, yet they have incredible power. Wish the surveillance state would establish meaningful guide rails (but it never will) or just topple