Weekly Real Estate News

Serious delinquencies on Federal Housing Administration-insured mortgages are putting renewed pressure on first-time and lower-down-payment homeowners, with the Houston area showing signs of stress as insurance, utilities and other household costs rise.
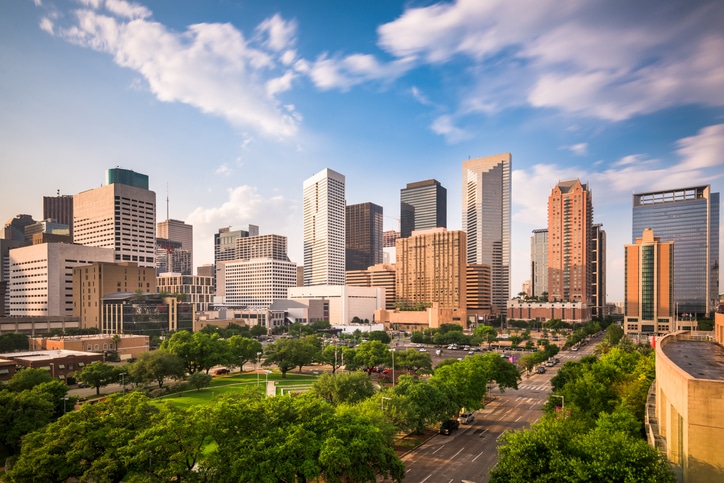
In the Houston metropolitan area, 1,583 of 50,627 FHA-insured loans in a recent origination cohort were at least 90 days past due as of August 2026, according to HUD figures analyzed in an October 9 report by the Houston Business Journal. That is approximately 3.1% of the loans in the cohort. The measure covers FHA loans with amortization beginning from September 2024 through August 2026; it is not a delinquency rate for every Houston mortgage or every FHA loan outstanding.
FHA borrowers face pressure beyond the mortgage payment
The report also cited a national FHA serious-delinquency rate of approximately 3.3% at the end of the second quarter, up from a year earlier. It attributed much of the pressure on borrowers to higher costs for insurance, energy and everyday necessities.
These figures require careful comparison: the Houston percentage comes from a defined recent-loan cohort, while the national percentage refers to the broader FHA portfolio. They should not be treated as perfectly comparable measurements.
FHA-insured mortgages are designed to expand access to homeownership, often allowing qualified borrowers to purchase with relatively small down payments. But lower cash reserves can leave households vulnerable when homeowners insurance, property taxes and living costs rise after closing.
Regional differences matter
The same report identified substantially higher serious-delinquency rates among recent FHA loans in some markets, including Detroit, Baton Rouge, Philadelphia and Chicago. Those differences underscore why national averages alone may miss localized financial strain.
For mortgage originators and servicers, a borrower who qualified at closing may still experience payment difficulty when non-mortgage expenses increase. Early borrower contact, accurate escrow projections and appropriate loss-mitigation options can become increasingly important when delinquency rates rise.
Serious delinquency does not automatically mean foreclosure. FHA servicing rules provide pathways to evaluate borrowers for home-retention assistance, and the outcomes depend on individual circumstances and program eligibility.
The emerging concern is not a uniform collapse in mortgage performance. It is the uneven impact of rising ownership costs on households with limited financial cushions. Additional HUD portfolio releases and Mortgage Bankers Association delinquency reports will help show whether the stress is broadening.