Weekly Real Estate News
Distress in a major segment of the commercial mortgage-backed securities market edged higher in October, even as the share of loans at least 30 days delinquent declined slightly, according to new data from KBRA.
The ratings agency’s October 30 report found that the distress rate across its rated U.S. private-label CMBS universe increased four basis points from September to 10.3%. The delinquency rate declined two basis points to 7.7%, representing approximately $25.7 billion in loans.
Distress and delinquency tell different stories
KBRA defines distress to include delinquent loans and loans that remain current but have moved into special servicing. As a result, the 10.3% distress figure should not be described as a 10.3% delinquency rate.
Both headline measures were lower than a year earlier: delinquency declined 24 basis points year over year and distress fell 52 basis points. The October increase in distress was therefore a modest month-over-month move rather than a new year-over-year high.






Office and conduit loans face pressure
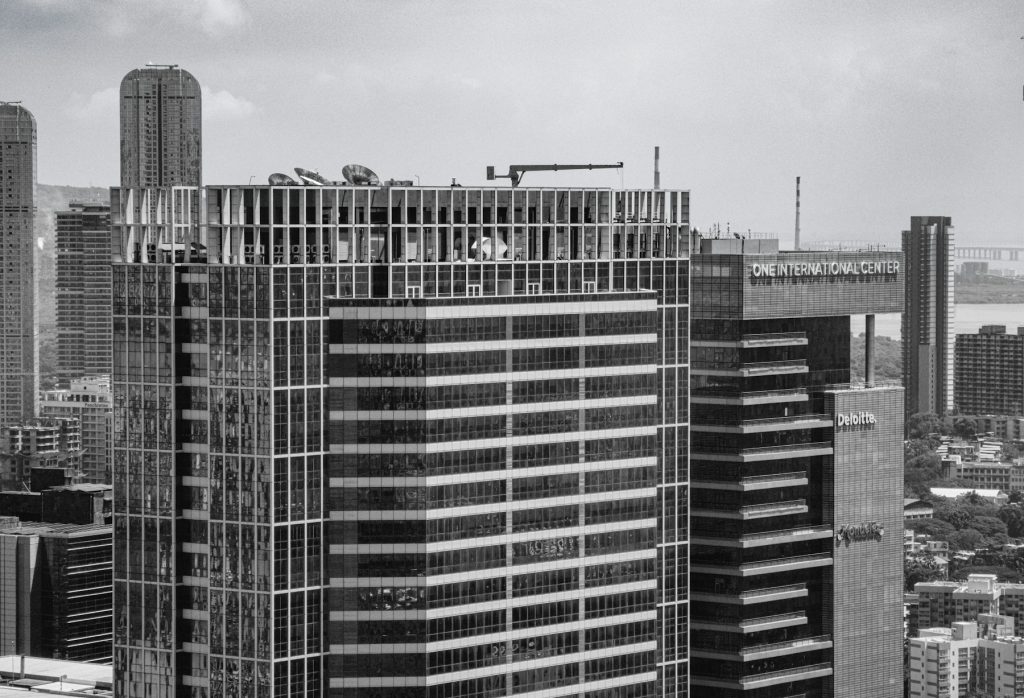
Conduit CMBS distress increased 19 basis points to 12.5%, compared with a relatively steady 5.8% for single-borrower and large-loan transactions. Office distress increased 11 basis points as several sizable loans became delinquent.
Among the newly delinquent office exposures KBRA identified were 101 Hudson Street, with $250 million across five conduit transactions; Huntington Center, with $126 million across three; and 80 Park Plaza, with $116.3 million across four. The agency also identified offsetting improvements and dispositions, including the removal of the 225 Bush Street loan from the distressed pool.
Mixed-use distress increased 41 basis points, with newly delinquent and specially serviced properties contributing to the move.
What the data cover
The report examines approximately $344.5 billion of KBRA-rated U.S. private-label CMBS, including conduit, single-asset/single-borrower and large-loan deals. Its delinquency and distress percentages are calculated against non-fully-defeased loan balances. The figures are not a measure of all U.S. commercial real estate mortgages.
For lenders and investors, the distinction matters: borrowers can be current on payments while facing refinancing, maturity or property-level issues that require special servicing.
Simple Content Summary
KBRA reported a 10.3% distress rate in its rated private-label CMBS market in October 2026, up four basis points from September, while the delinquency rate eased to 7.7%. Office and conduit exposures remained areas of concern. Both headline rates were lower than a year earlier.