Weekly Real Estate News
Summary
Compass data show 92% of San Francisco single-family homes sold above asking in September, while statewide sales fell 6.5%. San Francisco prices and bidding competition diverged sharply from softer Santa Clara and Sacramento-area markets. Figures describe September transactions, not a new October 26 event.
Nearly nine in ten San Francisco single-family homes sold for more than their asking price in September, a striking exception to the softer demand and growing buyer leverage seen in many other U.S. housing markets.
The figure comes from Compass International Holdings’ Northern California market report, released October 9. Its September data show that 92% of San Francisco single-family sales closed above list price. The city’s median single-family price increased 17% from a year earlier, while its condominium median rose 23%. These are September transactions reported earlier this month, not a new October 26 sales release.
The contrast extends across the Bay Area. Compass found that 63% of single-family sales in San Mateo County closed above asking, while Santa Clara County recorded a 4% decline in its single-family median, 15% more active listings and a 49% increase in price cuts. The difference underscores why a single national housing narrative can miss local market extremes.






San Francisco’s shortage creates a different market
San Francisco’s inventory remains constrained even as the traditional fall listing season adds properties. Compass reported a 62% month-over-month rise in new single-family listings from August, but the increase should not be mistaken for abundant supply: available inventory and new-listing flows are different measures, and new homes can sell quickly.
The condo market also strengthened. In September, 66% of San Francisco condominiums sold above their asking prices, up 27 percentage points from a year earlier, according to Compass. Condos have lagged single-family houses in many markets, making that shift notable.
Separate Redfin housing-market data show a 14.9% year-over-year increase in the city’s median sale price over the three months ending in September. Redfin’s figures cover all home types and use a different period and methodology than Compass’s single-family September statistics. They should not be treated as interchangeable.
Elsewhere in California, the market is slowing
The California Association of Realtors’ October 19 report found statewide existing single-family sales fell 6.5% from September 2025, to a seasonally adjusted annual rate of 260,410. The statewide median price increased just 1.7% to $899,720. The association attributed weaker demand to higher borrowing costs and affordability constraints.
California’s statewide sales-price-to-list-price ratio was 98.8% in September, according to the association. That is a different statistic from the share of homes closing above list price, but it reinforces the broader picture of a market where asking prices often remain negotiable.
Within the Bay Area, Compass identified tighter conditions in San Francisco, San Mateo, Marin, Alameda and Sonoma, while Santa Clara, Sacramento, Placer, El Dorado, Solano and Napa showed more signs of buyer leverage. The brokerage also reported a 34% increase in price reductions in Sacramento County, a 37% rise in Placer and a 32% increase in El Dorado.
What agents, lenders and buyers should watch
For agents, the lesson is not to apply statewide averages to individual listings. A competitive San Francisco house and a property in a market with rising inventory may require very different pricing and negotiation strategies. A home selling far above its list price does not by itself establish that its market value rose by the same percentage: sellers sometimes deliberately list below anticipated value to attract multiple offers.
For mortgage professionals, the divergence matters for appraisal expectations, borrower cash requirements and transaction timing. Buyers facing aggressive bidding may need additional liquidity beyond a lender’s valuation, while borrowers in softer markets may have more negotiating room for concessions or repairs.
September closings also reflect contracts negotiated earlier, before some of October’s latest mortgage-rate and market developments. The coming weeks of pending sales, inventory and price reductions will be more useful than a single month’s bidding statistics in determining whether San Francisco’s exceptional competition persists.
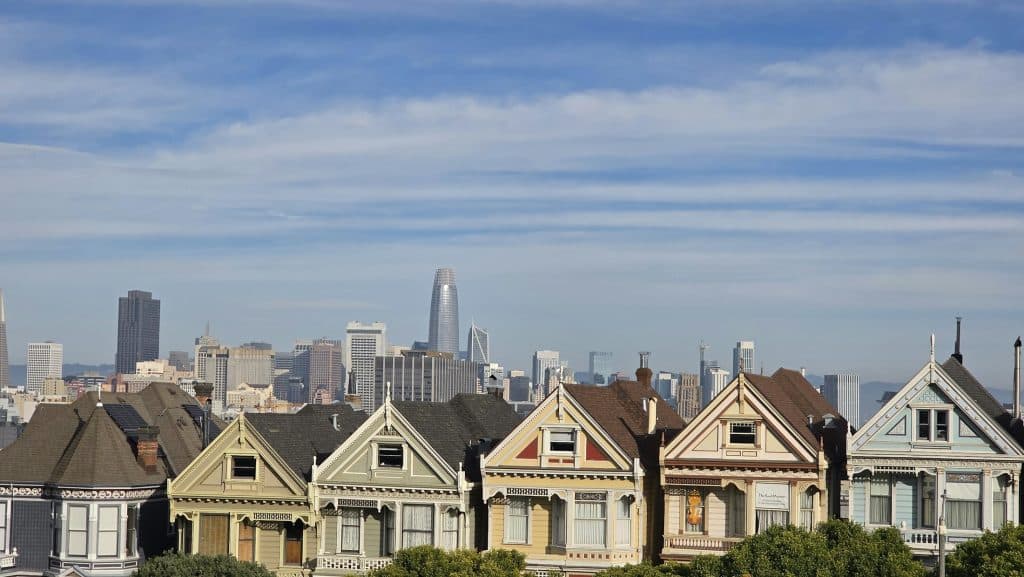
Sources: Compass International Holdings, Northern California Market Reports, October 9, 2026; California Association of Realtors, September Sales and Price Report, October 19, 2026; Redfin San Francisco housing-market data. September figures are not October 26 transactions. Featured photograph is an illustrative view of San Francisco, not a property involved in a reported sale.