Weekly Real Estate News

Summary
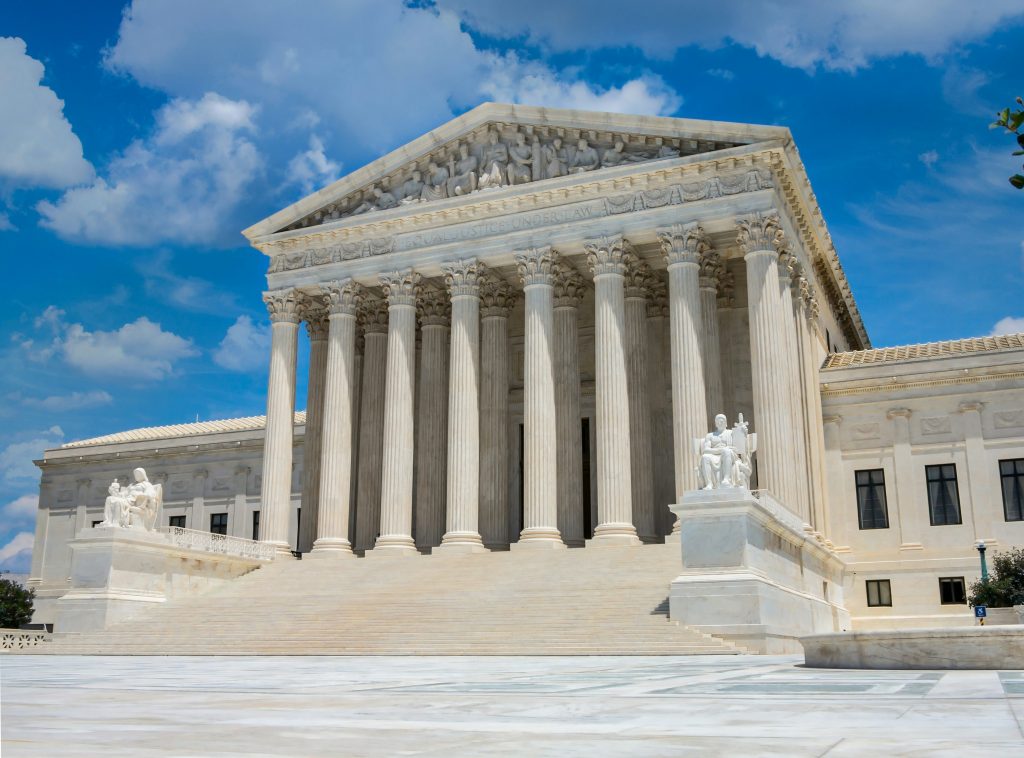
The U.S. Supreme Court asked the Solicitor General to weigh in on three cases over whether the National Bank Act preempts state requirements that national banks pay interest on mortgage escrow balances, after federal appeals courts reached conflicting results.
The U.S. Supreme Court has asked the Solicitor General to weigh in on three mortgage-escrow cases that have produced conflicting appellate rulings over whether federal law shields national banks from state requirements to pay interest on borrowers’ escrow balances.
The Court issued the requests Monday in Cantero v. Bank of America, Citizens Bank v. Conti and Flagstar Bank v. Kivett. In each case, the justices invited the Solicitor General to file a brief expressing the views of the United States.
That procedural move is significant, but it is not a decision to hear the cases. The Supreme Court has not granted certiorari in any of the three petitions. There is also no formal deadline for the Solicitor General to respond.
The dispute matters to mortgage lenders and servicers because it reaches a recurring cost of homeownership: money borrowers deposit into escrow accounts for property taxes and insurance. A number of states require financial institutions to pay interest on those balances. National banks argue that some of those state mandates are preempted by the National Bank Act because they interfere with federally authorized banking powers.
A circuit split after the Supreme Court’s 2024 ruling
The cases arrive at the Court after lower federal courts reached different results while applying the Supreme Court’s own 2024 decision in Cantero.
In that earlier ruling, the justices rejected the Second Circuit’s categorical approach to National Bank Act preemption. The Supreme Court said courts must conduct the type of practical analysis required by the Dodd-Frank Act and the Court’s Barnett Bank precedent, asking whether application of a state law “prevents or significantly interferes” with a national bank’s exercise of its powers.
On remand, the Second Circuit again sided with Bank of America. In May, it concluded that New York’s law requiring 2% interest on certain mortgage escrow balances is preempted as applied to national banks.
The First Circuit went the other direction in Conti. In a September 2025 decision involving Citizens Bank, the court held that the bank had not established that Rhode Island’s interest-on-escrow law was preempted. The court vacated dismissal of borrower John Conti’s lawsuit and sent the case back for further proceedings.
The First Circuit emphasized that Citizens had not identified an express conflict between the Rhode Island requirement and the National Bank Act and had not shown that the state law’s practical effects significantly interfered with the bank’s federal powers.
The Ninth Circuit’s Kivett litigation adds California to the conflict. That case concerns California’s requirement that lenders pay interest on certain mortgage escrow accounts and presents another route for the justices to address the preemption question.
The result is a problem national banks have repeatedly warned about: materially different obligations depending on the state and federal circuit in which a mortgage is serviced.
OCC has already taken a broad position on escrow interest
The litigation is unfolding alongside a major regulatory development at the Office of the Comptroller of the Currency.
In May, the OCC issued a preemption determination addressing state interest-on-escrow laws. The agency concluded that federal law preempts specified state laws that require national banks and federal savings associations to pay interest or other compensation on certain real-estate escrow balances or restrict fees associated with those accounts.
That determination has itself become the subject of litigation. A coalition of 10 states — Oregon, New York, California, Connecticut, Maine, Maryland, Massachusetts, Minnesota, Rhode Island and Vermont — sued in federal court in Oregon in August seeking to invalidate the OCC action.
The Supreme Court’s request for the Solicitor General’s views therefore comes at an unusually important moment. The federal government’s brief can address not only the competing appellate rulings but the relationship between the National Bank Act, Dodd-Frank’s preemption provisions and the OCC’s current regulatory position.
What the Supreme Court is deciding now
The immediate question before the justices is whether to hear one or more of the three cases — not whether banks ultimately must pay escrow interest.
A request for the views of the Solicitor General, commonly called a CVSG, allows the federal government to advise the Court on whether review is warranted and how it views the underlying federal-law issue. The Court can later grant or deny one or more petitions after receiving that input.
The Supreme Court’s Oct. 5 order list confirms the action. The Court’s docket in Cantero records the same-day entry: “The Solicitor General is invited to file a brief in this case expressing the views of the United States.”
The government has no stated filing deadline. Once the Solicitor General responds, the cases can return to a Supreme Court conference for consideration.
If the Court ultimately takes the dispute, the next ruling could have consequences beyond the amount of interest credited to an individual escrow account. The cases test how courts should apply Dodd-Frank’s limits on National Bank Act preemption when state consumer-finance laws regulate the terms of products offered by federally chartered banks.
Until that question is settled, national banks operating across multiple states remain caught between conflicting appellate decisions, an aggressive OCC preemption determination and state officials defending their authority to require interest on borrowers’ escrow funds.